Translate

Sunday, 28 August 2016

From Jackson Hole with Neutral Rate, Inflation Expectations, and Inflation Targets


 With interest rates around the world at close to zero or negative and another recession looming on the horizon central banks, having exhausted their firing powers with the so-called unconventional policies, appear rather anxious about the efficacy of their tools. This is why the Chair of the Federal Reserve, Janet Yellen, spent much of her speech at central bankers meeting in the mountain resort of Jackson Hole, Wyoming   trying to explore  the  effectiveness of Fed's expanded monetary policy toolkit.

Overall, it appears that Fed still thinks or hopes  that changes in nominal variables stemming from the conventional and unconventional policy tools such as changes in the Fed funds rate or Quantitative Easing will exert a lasting and  long-term impact on the real variables such as the real GDP growth rate in these financially  abnormal times. Ignoring the fact that the effectiveness of monetary policy tools has been seriously diminished in recent times at various advanced countries and abstracting from the distortionary effects of the unconventional tools on the economy, Ms. Yellen  primary message at Jackson Hole was that:

I expect monetary policy will continue to play a vital part in promoting a stable and healthy economy. New policy tools, which helped the Federal Reserve respond to the financial crisis and Great Recession, are likely to remain useful in dealing with future downturns.

There were hardly any new information about the exiting tools  or their effects on the transmission mechanism of monetary policy in the speech. However, the Chair mentioned that  future monetary policymakers might choose to explore some additional tools that have been employed by other central banks,  such as  the possibility of purchasing a broader range of assets,  raising the FOMC's 2 percent inflation objective or implementing policy through alternative monetary policy frameworks, such as price-level or nominal GDP targeting. She added  "adopting these policies would require a very careful weighing of costs and benefits and, in some cases, could require legislation".

Among these various alternative policies only the idea of targeting for a higher inflation rate will be materially different, and extremely harmful, the rest like  price-level or nominal GDP targeting are basically red herrings.  The idea of opting for a higher inflation target was recently floated by the president of the San Francisco Fed, John Williams, who has argued in the post-financial crisis world the significant decline in the natural rate of interest over the past quarter-century to historically low levels pose significant challenges for the conduct of monetary policy, defining the concept of the medium-term value of the natural  as the real interest rate that balances monetary policy so that it is neither accommodating nor contractionary in terms of growth and inflation in an economy at full strength.

Despite its shortcomings in describing the Wicksellian  concept of Natural Rate of Interest  Williams' concept as an equilibrium interest rate can be thought of as the rate of interest corresponding to a configuration of interest rate, output growth rate, inflation rate, employment and exchange  rate in a model in which goods and services, labour  and money&credit markets all are in equilibrium and in the currency market the covered interest rate parity condition is satisfied.  In  other words, this is the interest rate that prevails in an  economy operating  at its  production efficiency frontier. Williams believes this natural rate has declined and writes:
The new challenge for central banks is how to deliver stable inflation in a low r-star world. This conundrum shares some characteristics and common roots with the theory of secular stagnation; in both scenarios, interest rates, growth, and inflation are persistently low (Summers 2015).
This is also a belief shared by Ms. Yellen, who citing  Lubik and Matthes (2015), Laubach and Williams (2016), and Johanssen and Mertens (2016) states "there is empirical evidence to support the conclusion that the neutral rate is currently not far from zero". This is indeed a remarkable inference, since it implies that  in spite of the existence of a relatively large output gap,  the interaction of the economy's aggregate demand and the long-term aggregate supply function on the space spanned by the   real interest rate and real output variables has shifted down to a close-to-zero interest rate. It should be noted, however, that this inference  appears to have been drawn from a conjecture, as she writes:
 we know that the neutral rate must have been well below its historical norm in recent years, because with the actual real interest having been as low as it has been lately, the economy would have otherwise expanded much more than has been the case. 
This conjecture would be flawed if the potential output growth rate has been slowing down due to a lack of capital formation stemming from the prevailing uncertainty. As we have argued before there is strong evidence that in such circumstances businesses in their capacity planning would be refraining from investing in irreversible capital expenditures, and this is the main cause of lower growth rate at the lower actual real interest in the recent times.

In fact, based on the following chart from Holston, Laubach, and Williams (2016) one can infer that the Wicksellian natural rates  in the US, UK and euro area  over the period 1980-2007 have been close to 3, 2.5 and 2 per cent respectively and the apparent decline  since 2008 is basically an art effect  stemming from a drastic structural change in financial markets in recent years. In other words, the fluctuation around the above mentioned estimated natural rates are caused by various cyclical factors. Moreover, given that natural rate is an equilibrium concept it does not stand to reason to argue that it demonstrates such an extreme volatility over short spans of time.

Estimated inflation-adjusted natural rates of interestSource: Holston, Laubach, and Williams (2016); data are four- quarter moving averages

As we have argued in the past, the concept of neutral rate is a long-run phenomenon associated with potential output at equilibrium. When the economy has been  in a prolonged state of disequilibrium and uncertainty as a result of which  businesses have revised and delayed their capital expenditure plans then the concept of  a lower neutral rate  would be vacuous. In such circumstances the potential growth rate would be lower due to the fact that production efficiency frontier is shrinking, and businesses are not investing toward minimizing their long-run minimum average cost. The stimulative monetary policy becomes ineffective because it cannot stimulate investment and capital formation. The distortionary impacts of flawed policies create bizarre relationships, for instance lower interest rates will encourage more savings because of consumers anxiety about the viability of their pension plans. On the investment side corporation decide to buyback their own share instead of investing and many decide to operate under intensive margin.

The idea that the natural or the neutral rate has declined is of course the dual form of the argument concerning the  progressive ineffectiveness of unconventional tools such as QEs or forward guidance. On her June 6th speech in Philadelphia Ms. Yellen, has referred to this ineffectiveness as less stimulative,  reporting:

The current stance of monetary policy is stimulative, although perhaps not as stimulative as might appear at first glance, 
which she has explained it in terms of a decline in the neutral rate. Similarly, Mr. Williams attributes this ineffectiveness to the "less room" conventional monetary policy has  "to stimulate the economy during an economic downturn, owing to a lower bound on how low interest rates can go. He states:
Although targeting a low inflation rate generally has been successful at taming inflation in the past, it is not as well-suited for a low r-star era. There is simply not enough room for central banks to cut interest rates in response to an economic downturn when both natural rates and inflation are very low.

In other words, Mr. Williams  argues that higher inflation rate would provide the monetary authority with a wider interest rate margin to be used as the policy instrument to fight the upcoming recession. Of course, if inflation rate target is arbitrarily raised to say 4 per cent the monetary policy would not automatically become effective in stimulating investment and exports. After all, we have experienced periods of stagflation and currency wars when monetary policy was ineffective.   Furthermore, his argument ignores the fact that what matters is the information content of prices, and this content diminishes at higher inflation rates due to the increased inflation variability. As Okun (1971) has shown variability of inflation rises with the inflation rate, and therefore the information content that allows the two sides of the market to plan and to execute their consumption and production decisions will deteriorate. The result would be lower growth rates.


Total debt securities, by residence and sector of issuer,
Amounts outstanding at end-September 2015, in trillions of US dollars
AU = Australia; CA = Canada, CN = China; DE = Germany; ES = Spain, FR= France; GB = United Kingdom; IE = Ireland, IT = Italy; JP = Japan; KR = Korea; KY = Cayman Islands; NL = Netherlands; US = United States. 
Sources: National data; BIS debt securities statistics.

Trimmed Mean One-year PCE Inflation Rate,
Source Federal Reserve Bank of Dallas


Relying on a partial equilibrium analysis based on the conventional expectations-augmented, or a New Keynesian, Phillips curve in which actual inflation trends depend largely on inflation expectations, and considering the fact that for two decades inflation  has been relatively  stable, Ms. Yellen has argued that:
The most convincing explanation for this stability, in my view, is that longer-term inflation expectations have remained quite stable. So it bears noting that some survey measures of longer-term inflation expectations have moved a little lower over the past couple of years, while proxies for these expectations inferred from financial market instruments like inflation-protected securities have moved down more noticeably. It is unclear whether these indicators point to a true decline in those inflation expectations that are relevant for price setting; for example, the financial market measures may reflect changing attitudes toward inflation risk more than actual inflation expectations. But the indicators have moved enough to get my close attention. If inflation expectations really are moving lower, that could call into question whether inflation will move back to 2 percent as quickly as I expect.

However, considering the fact that the expected inflation rate usually constitutes the intercept of a  Phillips curve  with the inflation axis in the space spanned by inflation rate and the GDP growth rates it would be natural for this supply side relationship to generate lower expected inflation in response to a persisting output gap. The main reason why inflation expectations and actual inflation were closely connected prior to the mid-1990s was the relative consistency of such shifts that was enhanced by the relative stability of the potential output growth. Wheres according to a study by the  Fed economist Jeremy Nalewaik
Movements in inflation expectations now appear inconsequential since they no longer have any predictive content for subsequent inflation realizations,
The reason for this break up is of course  the greater variability of the gap measure due to the utilization of the contingent  capacity that makes the Phillips curve shift  rather erratically.  At the same time the  aforementioned erratic fluctuation  of  the capacity growth rate caused again by the utilization of the contingent capacity results in the erratic behaviour of the actual inflation rate.

Thus, the key to the effectiveness of monetary policy is economy's return to the efficient production frontier, through a healthy capital formation, which would result  in higher growth of productivity. Unfortunately Ms. Yellen just in passing and almost as an after thought referred to the question of productivity growth in her Jackson Hole lecture :
Finally, and most ambitiously, as a society we should explore ways to raise productivity growth. Stronger productivity growth would tend to raise the average level of interest rates and therefore would provide the Federal Reserve with greater scope to ease monetary policy in the event of a recession. But more importantly, stronger productivity growth would enhance Americans' living standards.

We will be dealing with this issue in our next post.

Sunday, 14 August 2016

Can Deploying Helicopter Money Win the Currency Wars? Qua deinde fugam ?!


In response to the global financial crash of 2008, monetary authorities in the US, Eurozone, UK, Japan and China have implemented  QE plans to purchase massive quantity of bonds to jump start their economies. However, the programmes soon morphed into full-fledged currency wars.

 Following the February Shanghai G20 meeting,  monetary authorities, under the US auspices decided  not to  pursue exchange rate depreciation in a beggar-thy-neighbor approach. For a while it appeared that there was a halt in the currency wars.  However, with the global slowdown in the first half of 2016 and the Fed's delays in implementing its normalization policy, the market came to the view that the Fed is welcoming a weaker US dollar.

On August 4th, the British pound depreciated further after   Governor Carney  announced  that to mitigate the adverse effects of the Brexit referendum Bank of England would expand its bond purchase substantially  and buy not just more government bonds, but also corporate bonds.  A few days earlier, on July 29th, the Bank of Japan that  has been purchasing about 80 to 120 trillion yen (close to $1 trillion) of government bonds each year,  announced that it  would increase the scale of a program to buy exchange-traded stock funds to ¥6 trillion a year from ¥3.3 trillion, and it doubled the size of a dollar-denominated lending program aimed at Japanese companies operating overseas to $12 billion. However, the yen jumped 1.8 percent to 103.37 per dollar. We may recall that  on May 22nd, while denying that he is targeting exchange rate value of yen,  the bank’s governor, Haruhiko Kuroda, had said :
"If necessary, we can further ease our monetary conditions in three dimensions. Quantitative, qualitative and interest rates."
 It would be interesting to ask if the Japanese policy review in September will result in the resumption  of currency wars and will the helicopter money help UK and Japan to improve their economic outlook amidst of the current global slowdown?

Japanese Yen -US Dollar Exchange  Rate


British Pound - US Dollar Exchange Rate


In UK, the Bank of England, introduced its programme  under the banner of "exceptional package of measures" amidst of the current global slowdown. This move was taken by many as the signal that the Bank will do what is required for "monetary and financial stability".  The package included:
* a cut in the UK policy rate from 0.5% to 0.25%,
* a quasi-forward-looking guidance that interest rates could go lower (to near zero) by the year end, and
* a plan to buy £60bn worth of government bonds, extending the existing quantitative easing (QE) programme to £435bn in total, and £10bn of corporate bonds over an 18-month programme set to start mid-September in a bid “to impart broad economic stimulus”. Targeted companies would be those conducting “genuine business in the UK”, and not banks, building societies or insurers.
As a consequence bond yields have plummeted in the UK, for instance  the yield on its  longest-dated bond, the 2068 maturity, has declined from 2% on the day of the referendum to 1.06% on August 11, but any marked impact on GDP is highly doubtful. In the belief that the QE policy will lower interest rates and encourage investment and consumption of interest sensitive durable goods, thus boosting the GDP growth, the Bank has been buying bonds (gilt) at auctions in the market since 2009.

We have of course discussed in the past the dangers of negative interest rates, the adverse impacts of lower rates on savers and borrowers at such high level of debts, anemic productivity growth, widening  of current account deficit and lack of capital formation;  and thus will not dwell any further on these issues here. Suffice to remind readers that a year ago we had predicted the lower British economy's  growth, which we attributed  to these fundamental factors particularly a lack of productivity enhancing investment. We now notice that  the Bank has revised down   its growth forecasts  for 2017 from the 2.3%, expected in May, to 0.8%, in its recent announcement.


Bank of England's holdings of bonds (gilt), Source: Bank of England


Although, the British pound has been depreciating since the mid-2014 and the Brexit has given a boost to its decline, the bank's declared the new package's main aim was to mitigate the prevailing uncertainty. In the words of Governor Mark Carney:
"By acting early and comprehensively, the (Bank) can reduce uncertainty, bolster confidence, blunt the slowdown and support the necessary adjustments in the UK economy,"
The Governor, however, acknowledged that when rates are so close to zero the effectiveness of any further cuts on the economy would be diminished, thus restraining the impacts of interest rate cuts and quantitative easing.

UK's Labour Productivity, (pre-crisis peak=100)


UK Manufacturing Input Price Inflation, Annual Rate, Source: ONS


UK Unemployment Rate (Age 16 and over), SA

The Governor's warning was an important one, to the effect that a week later on August 10th when the bank tried to purchase its targeted £1.17bn of bonds it could not find enough sellers for a shortfall of £52m. This excess demand for bonds raised their prices and thus lowered their returns. In fact, yields on UK government bonds on 3 and 4 year turned negative  (to minus 0.017 and minus 0.015 percent respectively).

Despite the fact that the £52m excess demand for bonds was relatively a small sum, and the fact that the Bank assured the market  that it will make up the shortfall in the second half of its six-month purchase programme, the signal indicated that investors, seeing the low British  productivity growth and the current global output gap, were trying to hold on to their relatively safe higher-return bonds, particularly when interest rates are expected to fall in this uncertain times.

In short, savers  increasingly worrying about their future earnings are trying to save more.This implies that the  future shortfall in supply may need to be eliminated by the Bank's direct purchase of government bonds -- i.e, by helicopter money.

The new Chancellor of the Exchequer Philip Hammond may be using helicopter money to both prop up consumer demand and finance government's infrastructural projects. He  has abandoned plan to deliver a budget surplus by 2020 and has said "We have the option of a fiscal response,"  and he will be using the autumn statement,“to keep the economy on track.”

However in uncertain times  helicopter money is a dangerous  tool, particularly when the monetary authority's credibility is under  a heavy scrutiny.    Given that the Bank will be directly financing the infrastructural projects of the governing party, which depending on various electoral strategies are usually concentrated in certain constituencies under a political agenda, it will politicize the Bank -- which is supposed to be  an apolitical entity. The politicization could, most probably, destabilize  the economy, because it destroys the price discovery mechanism  of the market,  generating the risk of stagflation in the current challenging circumstances.
UK's Current Balances ( four-quarters cumulative) as a percentage of GDP


In Japan,  with its aging demography, and a population that  has been declining since 2008, the Bank of Japan's stimulative bond purchasing policies  has been totally  ineffective in generating growth. Moreover the adverse effects of  negative interest rates have already distorted the Japanese financial market. For instance, as a result of lack  of interest on a sale of 10-year Japanese government bond  its yield  has raised to 0.053 percent`from a negative  0.13 percent.

The distorted financial market in an  economy with a declining population, where Japan's fertility rate at 1.6 children is well below its replacement level of 2.1, can prolong the prevailing uncertainty. The situation is exacerbated by the fact that more than a third of the population is older than 60, with a high marginal propensity to save.

Although Japan’s economy  appears to have reached full employment at the unemployment rate of 3.1 per cent in June, there are indications that, like in the US and Europe, businesses are adopting intensive-margin production strategies and postponing  irreversible capital formation.  This is why Japan’s economy has been fluctuating between expansions and contractions in recent quarters, has a stagnating wage growth and  its businesses are hoarding cash that has reached the staggering level of US$3.4 trillion.

In these conditions,  exacerbated by the adverse effects of  the global slowdown the Japanese policy makers are trying to introduce a coordinated policy move with the Bank of Japan almost doubling its purchases of exchange traded funds (which include real-estate investment trusts, corporate bonds, commercial paper and stocks) and the Japanese  government introducing a fiscal stimulus package at a total value of ¥28 trillion ($273 billion) over several years,  that includes ¥7.5 trillion in new spending to jump-start the country's sluggish economy.

The intensified uncertainty, emanating from the negative interest rate policy and the Bank of Japan's announcement of an upcoming assessment of the effectiveness of its current stimulus policies in September has triggered a further appreciation of yen and a sell-off in the Tokyo stock market, as well as the worst sell-off in government bonds in more than three years, that has already impacted other countries bond markets.


Japan's economy grew by an annualized 0.2 percent in the second quarter (0.2 percent on a quarter-on-quarter basis),  well below the 0.7 percent increase markets had expected and a marked slowdown from a revised 2.0 percent increase in January-March. Household consumption, constituting about 60 percent of GDP, rose 0.2 percent, slowing from a 0.7 percent increase in the previous quarter, and  capital expenditure declined 0.4 percent after a 0.7 percent drop in the first quarter.

The September policy review may be a prelude to Japan's deployment of helicopter money in the currency wars, particularly  if the Fed continues to delay its policy normalization.


Japan's GDP Growth Rate, Quarterly- Seasonally Adjusted


Japanese  Government 30-Year Bond Yield


Wednesday, 3 August 2016

On the Vicious Circle of Global Slowdown and Banking Crisis


Reflecting the global nature of the financial malaise and its associated uncertainty, growth rates in most advanced countries have slowed in the second quarter. The slowdown may have triggered a global banking crisis.

More specifically, the U.S. GDP grew at a sluggish 1.2 percent rate in the second quarter as businesses continued to hold back on investments. Given a downward revision of the growth by the US Commerce Department to just 0.8 percent in the first quarter as compared to 1.1 percent that was previously estimated, the average growth rate for the first half of this year is just 1 percent. The US GDP growth for three consecutive quarters has been hovering close to 1 per cent.

The US GDP Quarterly Growth Rate

In the eurozone, the year-over-year growth in the second quarter slowed to 1.6%, relative to 1.7% in the first quarter, and the outlook has deteriorated rapidly with the uncertainties associated with Brexit and other geopolitical developments, such as the German-Turkish dispute after the recent coup and Russia's more assertive pasture. In Japan the GDP growth rate has swung between negatives and positives, averaging close to zero in recent quarters, and her second quarter annualized growth is expected to have dropped to near zero. The slowdown in China is also expected to be accelerated, due to its unsustainable debts and other imbalances.


This slow growth pattern should not be a surprise to the readers of this blog as we have persistently warned about the implications of businesses adoption of the intensive margin mode of production and delays in investing for capital formation arising from the prevailing uncertainty. The fact that in the US widespread slow growth in the second quarter was stemming from a fall in inventories, at a time when personal consumption was growing at 4.2 percent, has validated our hypothesis. Moreover, for the third consecutive quarter, nonresidential business investment in the US declined in the second quarter by 2.2 percent, indicating that businesses are refraining from the irreversible capital expenditures. The situation is not much different in the rest of the advanced countries.

In Japan, a ¥28 trillion ($273 billion) in new spending, announced in the early August, as part of the Second Arrow of Abenomics, meaning fiscal stimulus, to jump-start the Japan's sluggish economy is not expected to alter the global distortion of fundamentals. Precisely because of the uncertainty, Japan's $130 billion dollars worth of new fiscal stimulus, including cash payouts to low-income earners and increased infrastructure spending, earmarked for upgrading port facilities for cruise ships, as well as accelerated construction of a high-speed train line, is not expected to create much of incentives for capital formation in the country's export-oriented industrial sector. The only solution, as we have repeatedly called for in this forum, is a global accord to restructure the toxic debts and to realign various currencies based on the real purchasing power parity.

Unfortunately, the illusory appearance of a strong US labour market, with her unemployment rate at 4.9 percent, may have disguised the severity of the problem. The quasi-strength, however, is mainly due to the use of contingent labour in the intensive-margin capacity planning of businesses where firms substitute labour for capital due to uncertainty. This is exactly why wage growth has remained anemic. The slowing of global growth is setting into motion a vicious circle that could, with an increasing probability, trigger a global banking crisis.


As the following charts show European banks' shares have already plummeted to some distress levels as they are saddled with $1.3 trillion in non-performing loans, nearly $400 billion of them in Italy, and many don’t have sufficient capital buffer. The situation will dramatically worsen if the current slowdown develops into a highly probable global recession.

Barclays PLC

Royal Bank of Scotland Group


Deutsche Bank AG


Banco Santander SA

Monte dei Paschi di Siena

In spite of its convoluted narrative, the IMF's latest Global Financial Stability Report acknowledges that for many European banks, elevated non-performing loans comprise a major structural weakness. According to the report roughly one-third of listed European banks (by assets) are facing significant challenges to attaining sustainable profitability arising from legacy issues (900 billion of non-performing loans and an unspecified amount of toxic assets).
Deteriorating profitability and unresolved legacy challenges raise the risk that external capital and funding could become more expensive, particularly for weaker banks with very low equity valuations (price-to-tangible-book valuations of less than 60 percent), pointing to weak future prospects. Italian banks face a particular challenge in this regard, as market pricing has reflected investor concerns that some banks may face difficulties in growing out of their substantial NPL overhang, despite constructive steps taken by Italian authorities to facilitate balance sheet repair. 

Italy, like other eurozone's weaker economies, including Greece, Portugal, and Spain that have been severely afflicted by the Big Recession, most probably will experience acute distress and becomes the first major country fully exposed to the brunt of this vicious circle. During the six consecutive years of recession since 2007, Italy's GDP has declined by 10 per cent and the country's banks, that rely heavily on retail deposits and bonds to finance their lending, have accumulated about €400bn of non-performing loans, compromising more than 18 percent of their total loans.


The EBA tests did not include any banks from Greece or Portugal, . The two Irish banks, AIB and Bank of Ireland were among the worst financial institutions.The results will have adverse impact on plans to starting selling down the Irish government's stake in AIB next year. In the words of Philip Lane, Ireland's Central Bank governor: the two banks
are adequately capitalised but remain vulnerable to a downturn, especially in relation to the continued workout of problem loans and the sustainability under stress of current profitability levels.”

The Italian banks are already exhibiting the first signs of stress and with their eminent insolvency a global contagion of banks' failure would be inevitable. For instance, according to the recent EBA stress test, the oldest operating bank in the world: Monte dei Paschi di SienaBanca was the worst performing bank among the 51 participating banks in the test, requiring to raise massive amount of capital. The bank would be insolvent inthe European Banking Authority(EBA)'s stress test that was released on July 29th, with a common equity tier one (CET1) ratio of -2.44 per cent. Banks are central to the European financial system, supplying about three quarters of all credit, and their demise therefore will be a devastating blow to the economy in Europe.

The bail-in solution for banks on the verge of insolvency, suggested by the newly established EU’s banking union, that has become operative earlier this year, requires that the bank's shareholders , creditors and large depositors (i.e., in excess of €100,000) to assume a haircut before taxpayers' funds can be used to bail them out. Bondholders, of course dislike "bail-in" remedies, and many are concerned about the inconsistent and at times chaotic bail-in procedures that are adopted in trying to prevent bank failures. These policies have increased the risk of funding for smaller lenders. Moreover, the looming prospect of bail-in has diminished the supply of credit for the smaller lenders that are mainly concentrated in the weaker economies, exacerbating the banking challenges.


For instance, when the Italian government in 2015 decided to bail-in junior, or subordinated, bondholders at four small insolvent regional banks it generated a significant hardship for retail investors and pensioners because many of the banks’ junior bonds had been sold to them as riskless savings products. The move also frightened the investors.

To guard against a bail-in the board ofMonte dei Paschi di Sienahas approved a conditional recapitalization of the bank, guaranteed by a consortium of investment banks led by J.P. Morgan Chase. Nevertheless, the bank's prospects remain gloomy, particularly in the event of a global recession.

Impact on Common Equity Tier 1 (CET1) capital ratio from 2015 to 2018 in the adverse scenario by bank in alphabetical order.
Source: EBA


Evolution of absolute credit losses (€ bn) and contribution of cumulative credit risk losses in the adverse scenario for selected countries of the counterparty (%). Source EBA

According to a study byAcharya, Pierret and Steffen, to meet the robustness standards specified by the U.S. Federal Reserve, Europe’s largest banks, including HSBC Holdings PLC, Deutsche Bank AG and UniCredit SpA, would need to raise more than €253 billion in capital rising to more than €572 billion in a crisis situation. The study focusing on 34 of the largest European banks, with more than €23 trillion in assets, also found they would need to raise more than €1.19 trillion, potentially from governments, to have enough equity to withstand another financial crisis. According to the study:
A. French banks lead almost each book and market capital shortfall measure, both in absolute euro amounts and relative to its GDP. The capital shortfall ranges from €2 billion to €189 billion. The Capital Shortfall in a Systemic Crisis stress scenario (SRISK) suggests a shortfall of €248 billion, which corresponds to almost 12% of the country’s GDP

B. The banks with the largest SRISK next to France are from the U.K., Spain and Germany. While German banks benefit from a stronger domestic economy with a higher GDP and capacity for public backstops, shortfalls relative to the GDP of these countries is large corresponding to almost 11% in Spain and 7% in the U.K.

C. Italian banks have capital shortfalls of €97 billion, which correspond to about 6% of Italy’s GDP.
Notwithstanding these discouraging numbers, the results of EBA's stress test suggest that only a handful of banks will be facing the challenge of maintaining sufficient capital in the event of a hypothetical severe economic downturn. As a matter of fact, however, should a contagion scenario come to pass even the Acharya et al results would be too optimistic. The severity of European debts, anemic global growth, negative interest rates, currency wars, and a rapidly deteriorating international trade's outlook render the EBA results even-more questionable.

The world urgently needs a global financial accord to cleanse the system of its toxic assets, realign currencies, and reestablish trade links.


Tuesday, 26 July 2016

How the Federal Reserve will normalize the benchmark interest rate after its FOMC meeting of July 26-27

Despite the low probability that markets attached to a July rise of the target range for the benchmark federal funds rate, there was a good chance that Fed would have used the July window to raise the range to 50-75 basis points from its current 25-50 level. Given the ongoing presidential electoral campaign, Brexit-negotiation uncertainties, and the economic outlook in China and Japan; July meetings offered the only window for policy action in contrast to September or December schedules, that notwithstanding the high probabilities that markets attaches to them, appear quite problematic. In fact, with apparent improvements in the inflation rates and some economic data since late-June including the non-manufacturing ISM, employment, retail sales, industrial & manufacturing output, and existing home sales Fed appears to have been in a good position to send a serious message about its resolve to move toward policy normalization.

After seven years at the zero lower bound, the target range for Fed funds rate was raised by 25 basis points in December 2015. At the time the data were exhibiting similar improvements and yet the increase triggered some global market volatility earlier this year that could have been predicted.

In fact, last September we wrote;
The Fed indeed has created a catch 22 situation; as higher rates are needed badly, but any action towards raising rates would be extremely destabilizing.
The reason for the needed higher rates as we have stated in the past was that:
[T]he low rates have been distorting the economy and have created dangerous imbalances, particularly unsustainable level of debts.

We have argued that:
Unfortunately under today’s “currency wars” conditions, with the slowdown in China, and Europe’s debt crisis, as well as huge debt build up by consumers and states the normalization of monetary supply in any single country, as an isolated and uncoordinated action, would be a recipe for disaster,
and in particular have emphasized that:
Policy makers should realize how important the role of capital formation in the supply side is. They should realize that for a successful working of international trade currency values, like any other price signals, must be informative about their relative purchasing power, and these can only be discovered in transparent markets, where the fundamental relationships between financial assets and the real sectors are respected -- where the banks are healthy and tax payers are not on the hook for the rescue of Too-Big-to-Fail zombie banks.
Last September we argued that;
[T]o raise the policy rate by 25 basis point at this time would not send any useful signal and (...) could be a wrong move. A policy normalization would only make sense when the markets know what the normal level is and how fast is the speed of adjustment toward that level.


On May 19 the Federal Reserve Bank of New York has introduced a data product entitled  U.S. Economy in a Snapshot ,  that in the words of its president William Dudley is supposed "to provide information that helps households and businesses follow the data along with the Fed." Unfortunately. the package is silent about how to organize these data so that one can follow the Fed. One may argue that Fed itself is still struggling with the challenge of calculating the unobservable neutral rate. Mr. Dudley has explained that:
Conventional U.S. monetary policy is conducted by targeting the level of the federal funds rate—an overnight interest rate on bank reserves. Few participants in our economy have any direct interaction with this interest rate. How, then, is controlling this interest rate such an important part of setting monetary policy and steering an 18 trillion dollar economy toward the Federal Reserve’s dual mandate objectives of maximum sustainable employment and price stability? (...)

When asked about the trajectory for the monetary policy stance, I always point out that it is data dependent. The FOMC calibrates the stance of monetary policy to best achieve our twin objectives of price stability and maximum sustainable employment, taking into account our forecast for how the economy is evolving. This forecast reflects the ongoing flow of the data. Data releases that are close to our expectations have little additional impact on the forecast, while data releases that deviate significantly from our expectations can lead to more significant revisions of the forecast. It is, therefore, important for market participants and households to be able to follow the data along with the FOMC and to understand how we are likely to interpret and react to incoming data.


What does it mean to say that the monetary policy stance is data dependent? Simply put, it means that the Fed funds overnight interest rate, as the main policy instrument of the monetary authority, is determined in relation to the interactions among a whole set of data. It is the movement of the key macroeconomics variables and their impacts on each other that determines the equilibrium neutral rate.

In fact, a quick glance at the New York Fed's aforementioned and very useful publication reveals that it contains about 60 time series data depicting movements of various macroeconomics variables. How then one should look at these data, and how can one interpret their seemingly inconsistent movements at certain times in order to project the likely direction of the Fed funds rate?

How to project the likely direction of the Fed funds rate?

There are a number of ways that one could organize the key macroeconomics data. The most familiar way is to specify and estimate a small structural model. However, as we have argued before, in the aftermath of the financial crisis:
the macro models are not very well specified, simply because there have not been enough observations that would allow for control of the impacts of various QEs, zero- and-negative interest rates, global shocks and behavioral and policy changes – just to name a few (and assuming that we have a right theoretical model- which is a big assumption). Furthermore, we do not know what are the distribution shape of various arguments in our risk functions and so on.
Thus, an alternative way would be to use Bayesian priors and specify a calibrated structural model, that can be updated in a Bayesian learning process. Finally, one may choose a small subset of perhaps about 10 variables in a Bayesian Vector Autoregressive (BVar) model, or one of its variants that would determine with some probability how much the policy instrument is needed to be changed in order for the model to stabilize at a certain inflation target range and output growth level.


With this in mind, it is surprising that most often the discussions of the likely trajectory of interest rates setting by Fed is presented in various types of partial equilibrium analysis. Typically, many analysts employ a Wicksellian paradigm of natural rate of interest, which as we will argue later is totally irrelevant for analyzing a severely imbalanced economy, such as those of many advanced countries in North America, Europe and Asia. Moreover, at times the monitoring of various variables are presented outside any structural or time series model in an ad hoc fashion. For example Esther George, the president of the Federal Reserve Bank of Kansas City, in a May 12th speech in Albuquerque, N.M., reporting a decline to 5 % in the unemployment rate, from 10% in the aftermath of the financial crisis in 2009 has stated:
Of course, the unemployment rate is an imperfect measure of the labor market, so I also pay close attention to other data. For example, one development I find promising is that many individuals who had dropped out of the workforce are finding jobs. After the crisis, the percentage of people participating in the labor market fell sharply. Some of this is because our population is aging, so people naturally work less as they get older. However, some of the decline in labor force participation was due to workers being discouraged about their job prospects. More recently, however, we have seen an upswing in people finding jobs who had previously stopped looking for one. For example, close to 2 million workers returned to the labor force over the past six months. This pace of re-entry is close to the fastest pace in more than 15 years. Despite these positive developments, wage growth has remained sluggish and many people still feel like they have limited options in the labor market.
She then goes on to describe two business perspectives in the labour market,
One perspective is of a booming labor market, rising wages and an abundance of opportunity. The other perspective is of stagnant wage growth, limited upward mobility and job insecurity.
Relating the second perspective to a sharp decline in the share of workers in middle-skill jobs she argues that
As the Federal Reserve considers these and other economic trends, it must weigh a number of crosscurrents to determine the appropriate interest rate policy. In the shortrun, I continue to monitor how the energy, agricultural and manufacturing sectors are adjusting relative to the national economy. And over the longer-run, I evaluate what trends like job polarization mean for monetary policy.
Nevertheless, without specifying what would be the prevailing equilibrium long-run Fed funds rate, she concludes by stating that:
The current setting for the federal funds rate is well below what the FOMC expects will prevail in the longer term. The plan is to move gradually and in a way that is responsive to economic developments. I support a gradual adjustment of short-term interest rates toward a more normal level, but I view the current level as too low for today’s economic conditions.


The problem with this type of analysis is that if businesses are shifting towards intensive margin mode of the production due to uncertainty, using more labour intensive techniques in their short-term capacity planning, for example by introducing additional labour shifts or hiring contingent workers instead of investing in irreversible fixed capital, then the fact that many of the dropped out workers from the labour force are finding jobs would not be that promising.

Ideally of course the impacts labour participation rate, discouraged workers, or wage growth could be incorporated in a structural model, or alternatively the Fed can run small satellite models to estimate and inform the market of their likely impacts. These variables would affect the other key macroeconomic variables such as capital formation, capacity utilization, productivity, terms of trade; to name just a few. A partial equilibrium analysis ignores many of these impacts when the trajectory of these omitted variables under various scenarios can drastically alter the nature of analysis and the outlook.

As a result of ignoring the situation of uncertainty as well as not taking into account the impact of the businesses' shift to intensive margin mode of production as well as delays in investment plans President George in her speech in Oklahoma city of July 9th, 2015 had been too optimistic about the capital expenditure outlook, stating that:
Moreover, as the economy continues to heal and domestic demand continues to strengthen, businesses should have more incentives to increase capital expenditures.
As we know, this prediction of course has not come to pass as according to the most recent New York Fed's snapshot of the US Economy in July:
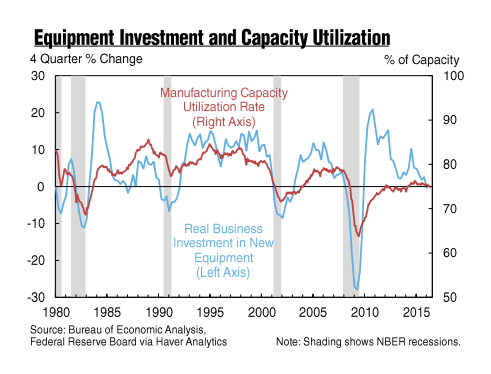
Over the four quarters ending in 2016 Q1, real business investment in new equipment was down 0.3%, continuing a slowing trend in place since 2010. (...) A key reason for the overall slow pace of growth of investment in new equipment is relatively low level of the manufacturing capacity utilization rate. This rate which had been slightly above 75% for over a year, dipped below 75% in May. Historically, robust growth of investment in new equipment is associated with a capacity utilization rate of 80% or higher.
As we have argued in September last year that :
The Fed's estimate of longer-run normal rate of unemployment is not consistent with the US investment in capital formation, The appearance of a gradual decline in the US economy's slack is attributable to a greater use of contingent labour and contingent capital, due to the prevailing global uncertainty.

The economy is being distorted by the zero-interest rate policy and is not getting closer to its long-term equilibrium. The use of contingent production factors has generated a quasi-closing of the gap in reference to a quasi-potential output growth, which corresponds to Klein (1960) and Berndt and Morrison (1981) definitions of capacity. This is why this quasi-closing of the gap has not exerted an upward pressure on the US inflation rate.
This structural approach would reveal that the question of capacity utilization rate needs to be carefully reevaluated. The nature of full capacity under contingent capital and intensive margin would result in a shift of the full capacity potential to the left along the economy's long-term average cost curve. The resulting short-run equilibrium would be different from the long-term equilibrium capacity. Furthermore we specifically stated that:
How can the labour markets move to equilibrium with such a weak capital formation? It is quite clear that this fragile capital formation is due to the prolonged period in which businesses have postponed investment as a result of the prevailing global uncertainties which have been exacerbated by the authorities suppression of equilibrating market dynamics . Investment spending has grown more slowly than usual for a business-cycle expansion and this is the main reason for the observed decline of the US productivity.

The global uncertainty and ultra-loose monetary policies have encouraged businesses to follow strategies of incremental reductions in costs that are not accompanied by investment in new technology. This has undermined the longer-term growth of potential output, which appears to have caused a distorted and artificial decline in real interest rate, by which authorities hope to encourage entrepreneurs to assume more risk. The economic theory suggests that lack of capital formation would cause a shrinkage in production possibilities frontier, resulting in a decline in labour productivity growth as we have observed in the US

Unfortunately in spite of recognizing that the long-run level of the neutral rate is highly uncertain many analysts, including some of the FOMC members, still focus on it. It appears that some even focus the highly volatile short-term rate. For example, the FOMC's minutes of the June 14-15 meeting reports that:
Many participants commented that the level of the federal funds rate consistent with maintaining trend economic growth—the so-called neutral rate—appeared to be lower currently or was likely to be lower in the longer run than they had estimated earlier. While recognizing that the longer-run neutral rate was highly uncertain, many judged that it would likely remain low relative to historical standards, held down by factors such as slow productivity growth and demographic trends.
It should be clear that it is not slow productivity growth that is holding back (the long-run) neutral rate. The direction of causality is the other way around. The prevailing low interest rate gives the impression that the neutral rate has declined, and at the same time they cause a delay in capital information, via a rise in uncertainty that low rates are causing. Low capital formation reduces the trend productivity, although due to intensive margin operation we may observe some transitory short-term productivity increase. As we have argued in the past, the neutral or natural rate of interest derived from the Wicksellian theory is only valid in the long run general equilibrium conditions. We stated that:
[T]he Wicksellian theory is a general equilibrium theory in which the financial rate of interest that borrowers actually pay must be equalized to the natural rate of interest that is determined by the marginal return on the fully employed real capital. If the financial rate is below the natural rate the demand for investment will rise as businesses can borrow at the lower financial rates and invest the funds into high-returning projects. However, the information signals that a Wicksellian paradigm could emit are not meant for a disequilibrium environment in which the real capital is underutilized and businesses are postponing investment in irreversible fixed capital and opt for waiting.
When due to the prevailing uncertainty businesses refrain from investment and when in their capacity planning they resort to utilizing contingent labour and capital instead of moving towards their long term minimum average cost capacity the Wicksellian equilibrium theory would be an inappropriate analytical framework. In fact, the concept of the natural rate of interest in a disequilibrium environment would be an oxymoron.
-- The introduction to this piece is slightly modified to take into account the Fed's inaction on July 27th.

Wednesday, 13 July 2016

The UK's Low Corporate Tax Rate; Will it Attract Investment?


What are the merits of George Osborne’s slashing of the UK’s corporation tax rate? In the previous coalition government he reduced both the main corporation tax rate (from 28% in 2010) and the small profits rate (from 21% in 2010) to 20% in 2015–16. After the Brexit vote the chancellor has argued for a drastic reduction of the rate to below 15 per cent in order to demonstrate that Britain is “open for business” to international investment? In an Opinion piece published on the Wall Street Journal , on July 10, Mr. Osborne wrote:
Now we intend to offer even more competitive taxes, and to become a home to more, not less, international business. To signal our intent, we will cut our corporate tax rate still further. It was already set to reach 17% from the 28% rate I inherited six years ago; now I want it to fall to 15% and preferably lower. What stronger message could we send that Britain is open to business?

 Will the lowering corporate tax policy improves British industry's competitiveness and enhance its productivity? Or would it likely exacerbate a zero-sum international race to the bottom between governments on tax rates as some have argued it would?


There has been a tendency throughout the advanced countries to reduce corporation tax rates since the stagflation of 1970s as the policy makers have tried to improve competitiveness and expand export markets. This tendency has been the most striking in the UK, where since 2010, it has cut tax rates deeper and at a greater speed than her competitors,  to the extent that as the following chart shows the rate is now among the lowest in the G20, and as we saw earlier may become the lowest if other countries do not respond.

Corporate Tax Rates Across G20

Source: IFS

As we have argued last August, the British economy is plaggued with underinvestment which is hampering its productivity growth and its competitiveness. Corporate tax rate reductions that are not being tied to the companies' investment in innovation and agility will just deteriorate the fiscal stance of the country and will add to uncertainty which would discourage capital expenditures.

Sources of Growth in the UK economy 

(year-over-year growth rate)

Source: Hover


The above chart indicates that UK investment has been decelerating at an alarming pace since the first quarter of 2015. As we have argued before, because of businesses’ utilization of contingent capacity the UK productivity has been misleadingly signaling some artificial improvements.  We argued:
This is because in planning for capacity during uncertain times businesses usually postpone their irreversible component of investment and utilize intensive margin production processes. As a result of this focus on short-term capacity corresponding to existing cost structure the longer-term capacity signals will be hidden. (...)
We argued that consistent with Ben Bernanke’s option price of waiting it would be quite rational for businesses to postpone their strategic investment plans at uncertain times and focus instead on their contingent capacity limits, which would result in transmission of inconsistent and misleading signals on capacity utilization rate and productivity improvement. A misinterpretation of these signals by policymakers would deepen and prolong uncertainty.

A corporate tax reductions cannot eliminate or mitigate such uncertainties and in contrast it may just add to them if other countries would retaliate by lowering their tax rates. In the meantime productivity growth — defined as the rate of change of output minus rate of change of hour worked — may continue to send false rising signals misinterpreted by policymakers as the indication that markets have agreed that the economy is open for the business and that the businesses are investing in innovation and competitiveness to expand the production possibility frontier. Whereas in reality because of postponement of real investment and utilizing contingent capacity the economy is falling behind.


Corporation Tax Rate In Selected Countries. Source: KPMG
UK's Corporation Tax Rate, 1981-2016

Germany's  Corporation Tax Rate, 1996-2016

US' Corporation Tax Rate, 2001-16

Friday, 8 July 2016

Why Interest Rates Are So Inconceivably Low?


In a recent article in the Washington Post professor Larry Summers has argued that the fact that the U.S. 10- and 30-year interest rates reached all-time lows of 1.32 percent and 2.10 percent on July 6th this year, as well as the record-low 10-year interest rates in Germany, France, Switzerland and Australia reflect a heightened recognition of the importance of the “Secular Stagnation” risks. He wrote:
There is a growing sense that the world is demand-short — that the real interest rates necessary to equate investment and saving at full employment are very low and often may be unattainable given the bounds on nominal interest rate reductions. The result is very low long-term real rates, sluggish growth expectations, concerns about the ability even over the fairly long term to get inflation to average 2 percent, and a sense that the Fed and the world’s major central banks will not be able to normalize financial conditions in the foreseeable future.

Thus, theoretically speaking, according to professor Summers the configurations of the supply and demand functions for investment funds now suggest a very low real interest rate  (most probably implying a negative rate at the full-employment level) which is unattainable due to the close-to-zero lower bound nominal rate. This argument as previously laid out by him and his co-authors Eggertsson and Mehrotra in Secular Stagnation in the Open Economy (NBER Working Paper No. 22172, April 2016) is based on Alvin Hansen’s idea of secular stagnation suggesting that:
the industrial world is plagued by an increasing propensity to save and a declining propensity to invest. The result is a declining equilibrium real interest rate, a tendency for lower bounds on interest rates to constrain their ability to find equilibrium levels, and a consequent persistence of inadequate demand leading to slow growth, sub-target inflation, and excessive non-employment.

Believing that the sluggish growth and low inflationary expectations are consequences of these low long-term real interest rates, Summers expresses concern that:

policymakers still have not made sufficiently radical adjustments in their worldview to reflect this new reality of a world where generating adequate nominal GDP growth is likely to be the primary macroeconomic policy challenge for the next decade.
But why there is an increase in global propensity to save? Are the interest rates providing relevant signals about the global saving propensity at the current sluggish economic environment? Moreover, what is the rationality for this bizarre economic agents' inter-temporal choice in such uncertain times? We note that Professor Summers' argument is grounded on the Swedish economist Knut Wicksell's thory of "Natural Interest Rate". Substituting the term "neutral rate" for the Wicksellian "natural rate" concept, he writes:
Secular stagnation occurs when neutral real interest rates are sufficiently low that they cannot be achieved through conventional central-bank policies. At that point, desired levels of saving exceed desired levels of investment, leading to shortfalls in demand and stunted growth.
We note that the Wicksellian theory is a general equilibrium theory in which the financial rate of interest that borrowers actually pay must be equalized to the natural rate of interest that is determined by the marginal return on the fully employed real capital. If the financial rate is below the natural rate the demand for investment will rise as businesses can borrow at the lower financial rates and invest the funds into high-returning projects. However, the information signals that a Wicksellian paradigm could emit are not meant for a disequilibrium environment in which the real capital is underutilized and businesses are postponing investment in irreversible fixed capital and opt for waiting.

When due to the prevailing uncertainty businesses refrain from investment and when in their capacity planning they resort to utilizing contingent labour and capital instead of moving towards their long term minimum average cost capacity the Wicksellian equilibrium theory would be an inappropriate analytical framework.  In fact, the concept of the natural rate of interest in a disequilibrium environment would be an oxymoron. The low and negative interest rates, are the prices savers are willing to pay to have access to a relatively less risky liquidity in these uncertain times. The factors influencing such inter-temporal preference is derived from a risk aversion motive.

As we have argued in the past, the economic agents are concerned about the precarious state of the global finance, the banking frailties, the high levels of various global debts, and a fast spread of political uncertainty. The sluggish growth and lack of demand are the consequences of a very disorderly structural adjustment in a perilous financial environment in which the old rules of the game have been abandoned and no new rules have yet been established.

The low interest rate thus is an indication of market assessment of the growth rate of potential output. As the following chart from Quartz show we have been in this situation also in the depression of 1930's.


This blog has referred in the past:
 “ to the suggestions of the prominent Swedish economist Gustav Cassel who in Brussels conference had recommended a re-balancing of the world flow of funds based on Purchasing Power Parity. A Cassel type of PPP adjustment does not necessarily require a gold-standard regime. A return to a Purchasing Price Parity can be grounded on a composite index of industrial materials. This process would create a realistic correspondence between the nominal world of finance and the real world of goods and services. A global annual GDP of 75 trillion dollars does not need to be lubricated by 600 trillion dollars of toxic assets."
We have also emphasized a need for restructuring of global debt and a need for a new global Marshall-type plan.  We also reminded the readers that:
in the eve of the London conference of 1933, the British Prime Minister Ramsay Macdonald, who understood the significance of the need for a global restructuring to establish a global financial balance, opined that the conference might possibly save democracy from the world’s economic challenges.”